Cointracking Is a Practical Guide to Crypto Tax Data Exports
Cointracking Is a crypto portfolio and tax reporting tool used to organize exchange trades, wallet transfers, income events, and exportable tax records. For users searching how Cointracking works, the core idea is simple: connect or import transaction history, review the data for accuracy, classify special activity such as staking or NFTs, and generate reports that can support tax preparation. It can reduce manual spreadsheet work, but users should still verify outputs with official records and qualified tax guidance.
Cointracking is best understood as a recordkeeping layer between crypto activity and the reports a person may need later. Many investors trade on centralized exchanges, move coins to self-custody wallets, receive staking rewards, test DeFi protocols, and occasionally buy or sell NFTs. Each action may create a different kind of data point. Cointracking helps collect those points into a timeline so balances, gains, losses, income, and transfers can be reviewed in one place.
Cointracking does not remove the need for judgment. Crypto tax treatment depends on jurisdiction, dates, cost basis methods, wallet ownership, and the specific facts of each transaction. The software can calculate and categorize based on imported information, but incomplete exports or mislabeled transfers can change the result. A careful workflow matters as much as the tool itself.
What is Cointracking used for?
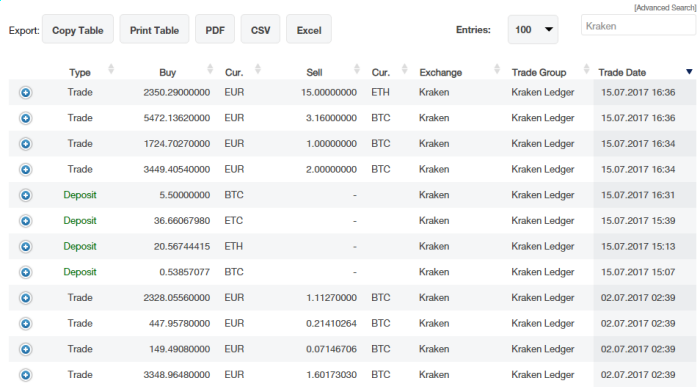
Cointracking is commonly used to track cryptocurrency portfolios and prepare exportable crypto tax reports. A user can bring in exchange files, wallet histories, and manual entries, then review the combined ledger. That ledger can help identify taxable disposals, non-taxable transfers between owned wallets, realized gains and losses, fees, and income events such as staking, mining, airdrops, or rewards.
Cointracking also serves people who need a historical view of their crypto activity. Instead of relying on one exchange dashboard, the user can see activity across multiple venues and wallets. This matters when assets move between platforms, because a sale on one exchange may need the original purchase price from another exchange to calculate a cost basis.
Cointracking can be useful before filing season, but it is not only a year-end tool. People who review their transaction history throughout the year often catch missing deposits, incorrect tickers, duplicate imports, and misclassified transfers earlier. That makes later reporting less stressful and gives an accountant cleaner supporting documentation.
How does Cointracking organize transaction data?
Cointracking works by turning many separate transaction records into a structured portfolio history. The user imports CSV files, connects supported exchange or wallet sources where available, or adds transactions manually. Cointracking then attempts to match buys, sells, trades, deposits, withdrawals, fees, and income so the portfolio view reflects what happened over time.
Cointracking generally needs the same basic information any crypto tax calculation needs: asset name or ticker, transaction type, amount, date and time, value in fiat currency, exchange or wallet source, and fees. When that information is present and consistent, Cointracking can calculate gains, losses, and income more reliably. When dates, prices, or transfers are missing, the user may need to edit the records.
Cointracking is especially sensitive to transfers. Moving Bitcoin from an exchange to a personal wallet is usually different from selling Bitcoin for dollars, but a file export may only show one side of the movement. If Cointracking cannot match the withdrawal and deposit, it may treat activity incorrectly until the user reconciles it. That is why reviewing imported data is not optional.
How do you export data from Cointracking for tax reports?
Cointracking can support tax preparation by producing reports and exports after the transaction history has been imported, reviewed, and categorized. The exact menu names and export formats can change, so users should confirm the current steps in the official Cointracking interface. The practical workflow is consistent: gather the complete data, check it, generate the report, and keep supporting records.
Cointracking users usually follow a process like this when preparing an export:
Import complete transaction histories from exchanges, wallets, and prior tracking tools.
Review balances against exchange statements and wallet explorers where possible.
Tag income events such as staking, mining, lending rewards, and airdrops carefully.
Generate tax reports or downloadable files for personal records or a tax professional.
Cointracking reports may include capital gains summaries, transaction lists, income details, and forms or worksheets that support filing. In the United States, crypto taxpayers often hear about Form 8949 and Schedule D for capital gains, while income may be reported elsewhere depending on how it was earned. This page is informational, not tax advice, and users should confirm requirements with current IRS guidance or a qualified professional.
What data should you check before relying on Cointracking?
Cointracking is only as accurate as the data it receives. The most important check is completeness. If one exchange account is missing, the cost basis for later sales may be wrong. If a wallet transfer is imported from only one side, Cointracking may flag a gap or interpret the movement in a way that does not match the user's intent.
Cointracking users should also review special transaction types. Staking rewards, liquidity pool deposits, token swaps, bridge transfers, wrapped assets, NFT purchases, gas fees, and margin activity can be more complex than a basic spot trade. Some events may need manual tags or edits. A clean import from a simple exchange account is very different from a year of on-chain DeFi activity across several wallets.
Cointracking can help surface these issues through warnings, balances, and transaction views, but the user remains responsible for verifying the story. Compare opening and closing balances, reconcile major transfers, and keep original CSV files or statements. For users building a broader recordkeeping habit, an internal guide to can help explain how those records fit together.
Why do crypto users choose Cointracking instead of spreadsheets?
Cointracking can save time because crypto records often become too large and irregular for a simple spreadsheet. A casual investor may have only a few trades, but active users can generate hundreds or thousands of rows through recurring buys, swaps, fees, staking rewards, and exchange transfers. Cointracking gives those rows a structure designed for crypto rather than forcing the user to build formulas from scratch.
Cointracking may also reduce arithmetic errors. Calculating cost basis, matching purchases to disposals, converting values into fiat, and summarizing gains by holding period can become tedious. Software does not guarantee correctness, but it can apply a consistent method once the inputs are clean. That consistency is useful when the same person files across multiple years.
Cointracking is also helpful for collaboration. A tax professional may not want screenshots from five exchanges and a half-finished spreadsheet. A reviewed export, transaction ledger, and report package can make the conversation more precise. The user can still provide original documents, but Cointracking gives the preparer a central reference point.
Is Cointracking safe to use with exchange and wallet data?
Cointracking safety depends on how the user imports data, what permissions are granted, and how account security is managed. CSV imports generally avoid live account permissions, but they require the user to handle files carefully. API connections can be convenient, but users should grant read-only access where possible and avoid permissions that allow trading or withdrawals.
Cointracking users should enable strong authentication, use unique passwords, and review official security guidance before connecting financial accounts. Crypto tax records can reveal balances, wallet addresses, trading habits, and personal financial history. That information deserves the same caution as bank statements or brokerage records.
Cointracking should not be treated as a place to approve transactions or store private keys. A tax and portfolio tool should only need historical data, not seed phrases or wallet recovery words. If any service asks for a seed phrase, that is a serious warning sign. Users should verify details directly with official Cointracking sources and avoid links from unsolicited messages.
How does Cointracking handle DeFi, NFTs, and staking?
Cointracking can record many kinds of crypto activity, but DeFi, NFTs, and staking often require closer review than exchange spot trades. Staking rewards may need income tags based on fair market value at receipt. NFT transactions can involve unique assets, royalties, marketplace fees, and transfers between wallets. DeFi activity can include liquidity deposits, withdrawals, rewards, bridges, and token wrapping.
Cointracking may import the raw entries, but a user may still need to decide what each entry represents. For example, adding funds to a liquidity pool is not always as simple as buying one coin and selling another. Some platforms produce receipt tokens, reward tokens, and separate fee records. Cointracking can help organize them, but users should not assume every complex transaction is automatically classified correctly.
Cointracking users with heavy on-chain activity should keep extra documentation, such as wallet addresses, protocol names, transaction hashes, and notes explaining unusual events. A companion page on can be useful for understanding why liquidity pools and token rewards often need more attention than ordinary exchange trades.
What are the main benefits and limitations of Cointracking?
Cointracking offers a practical benefit: it turns scattered crypto history into a reviewable data set. That can make portfolio monitoring and tax preparation more manageable. Cointracking can also help users spot missing data, estimate gains and losses, and prepare exports for personal records or professional review.
Cointracking has limitations too. Software cannot know every user's legal situation, cannot fix missing exchange records automatically, and cannot guarantee a tax outcome. Crypto regulations, reporting forms, and platform integrations can change. Cointracking users should check the current product documentation, confirm supported exchanges and wallets, and treat generated reports as a starting point for informed review.
Cointracking may be one option among crypto tax calculators, portfolio trackers, accounting platforms, and accountant-led workflows. Some users prefer a lightweight tracker, while others need a more detailed audit trail. The right choice depends on transaction volume, jurisdictions, asset types, and comfort with reviewing data. A user with ten exchange trades has different needs from someone using multiple wallets, bridges, NFT marketplaces, and staking platforms.
How should a new user get started with Cointracking?
Cointracking is easiest to use when the first setup is deliberate. Start by listing every exchange, wallet, and service used during the tax year. Include closed accounts if they had activity. Then download full transaction histories rather than short summaries whenever possible. Cointracking needs complete detail to connect purchases, transfers, sales, fees, and income events.
Cointracking setup should proceed in stages. Import one source, check balances, then add the next source. This makes it easier to identify where a mismatch begins. If everything is imported at once, duplicate rows and missing transfers are harder to isolate. For a new user, slower setup often produces a cleaner final report.
Cointracking should be reviewed before any report is shared or filed. Look for negative balances, missing cost basis, unexpected gains, unknown deposits, and transfers marked as trades. Then compare the final summaries with exchange statements and wallet records. The goal is not just to generate a file; it is to build a defensible transaction history that a person can understand.
Cointracking can be a useful part of a responsible crypto recordkeeping process when users treat it as a tool, not a substitute for verification. It can organize transactions, support tax report exports, and reduce manual work, especially across multiple exchanges and wallets. The strongest results come from complete imports, careful classification, security-aware setup, and confirmation against official tax rules and professional advice where needed.
Reader rating:
4.6 / 5
based on 497 ratings
Questions and Answers
What is Cointracking used for in crypto tax reporting?
Cointracking is used to organize crypto transaction history, track portfolio activity, and generate reports that can support tax preparation. Users import exchange trades, wallet transfers, fees, income events, and other crypto records. The software can then calculate gains, losses, and summaries, but the user should still review the data for missing entries, incorrect tags, and current tax requirements.
Does Cointracking automatically calculate capital gains and losses?
Cointracking can calculate capital gains and losses from imported transaction data when the records include accurate dates, amounts, fees, and values. The result depends on complete inputs and the selected cost basis method. If transactions are missing or transfers are misclassified, the calculations may need correction before reports are used for filing or professional review.
Can Cointracking handle staking rewards and DeFi transactions?
Cointracking can help record staking rewards, DeFi activity, and other complex crypto transactions, but these entries often need manual review. Rewards may need income classification, while liquidity pools, bridges, wrapped tokens, and NFT activity can create unusual records. Users should verify transaction tags, compare wallet histories, and keep supporting notes for complex on-chain activity.
Is it safe to connect exchange accounts to Cointracking?
Using Cointracking safely depends on security settings and import choices. CSV imports avoid live account permissions, while API connections should generally be limited to read-only access if supported. Users should use strong passwords, enable two-factor authentication, avoid withdrawal permissions, and never provide seed phrases or private keys to any tax or portfolio tracking service.
What should I check before exporting a Cointracking tax report?
Before exporting a Cointracking tax report, check that every exchange, wallet, and relevant service is included. Review unmatched transfers, duplicate imports, missing cost basis warnings, incorrect asset symbols, staking income, NFT trades, and DeFi entries. It is also wise to compare final balances with exchange statements and wallet records before relying on the report.
Is Cointracking a replacement for a tax professional?
Cointracking is not a replacement for qualified tax advice. It can organize records and create reports, but it cannot determine every user's legal obligations or guarantee a filing result. Crypto tax rules vary by country and can change over time. Users with significant trades, DeFi activity, business income, or uncertainty should consider professional guidance.
We use essential cookies to make our site work. With your consent, we may also use non-essential cookies to improve user experience and analyze website traffic. By clicking “Accept,” you agree to our website's cookie use as described in our
Cookie Policy
. You can change your cookie settings at any time by clicking “
Preferences
.”
Looking to switch from CoinTracking to Koinly? There are plenty of reasons to! Read our full comparison of
CoinTracking vs Koinly
, or follow the instructions below to export your CoinTracking data.
How to import data from CoinTracking to Koinly
The first step is to download all your data from CoinTracking and import it into Koinly. Here's how...
CSV
Follow these steps to download your Cointracking data:
Log in to CoinTracking.
Select
transactions
from the top menu.
Select
export
.
Select
CSV (full export)
from the drop down menu - be sure to select 'CSV (Full Export)' for a complete download of your data. Avoid clicking the standard 'CSV' option, as it does not provide the full export needed for a comprehensive migration.
Complete onboarding until you get to the Wallets page and find Cointracking in the list
Click on it and select "File import" in the import options screen
Upload the files you downloaded from Cointracking (one at a time) and click on Import
Review your transactions on the
Transactions
page to ensure everything is tagged correctly and no missing data
Go to the
Tax Reports
page to view your tax liability!
Notes / Limitations
While Koinly supports the CSV exports from Cointracking, there are a few things that need to be adjusted manually after importing:
Liquidity transactions need to be merged manually
NFTs need to be changed manually
Staking needs to be tagged manually
If you encounter any of these issues, we would recommend that you recreate the affected wallets on Koinly, in order for this to be handled automatically
Having trouble connecting Cointracking with Koinly?